Stats (all QOQ)
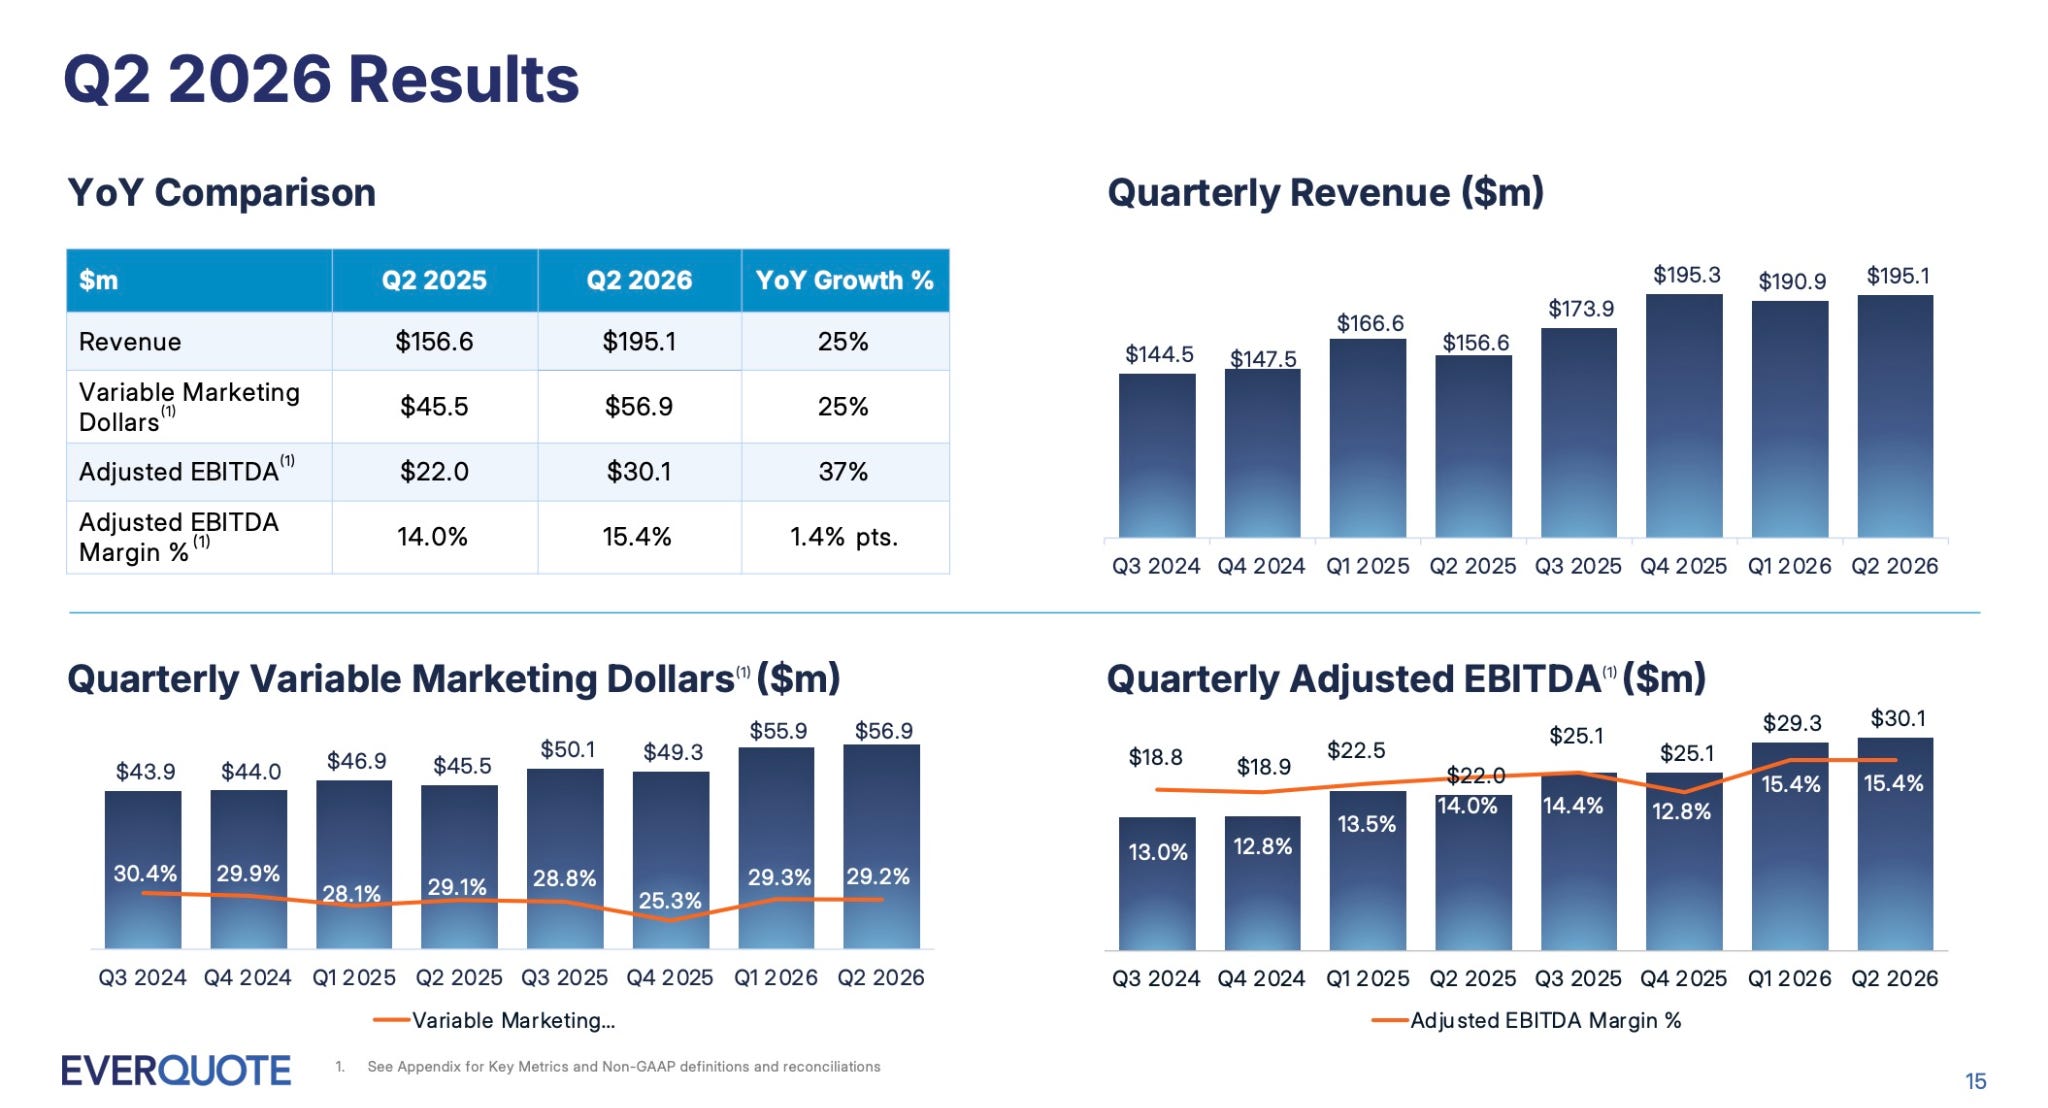
Revenue up 2%
EBITDA up 3%
Cash and equivalents up 8%
EPS up 6%
Assets up 5%
Home and Renters revenue up 25%
Five Observations:
1. EverQuote has been growing steadily
See chart from their earnings presentation - pretty solid uptick in growth. The Insurance sector had a bumpy run during COVID and for a bit after.
EverQuote now believes they’re close to hitting a billion a year in revenue.
From Joseph Sanborn, CFO
“We are executing well and remain confident in our ability to achieve $1 billion in annual revenues on the timeline we initially communicated to investors last November, while also generating strong cashflow.”
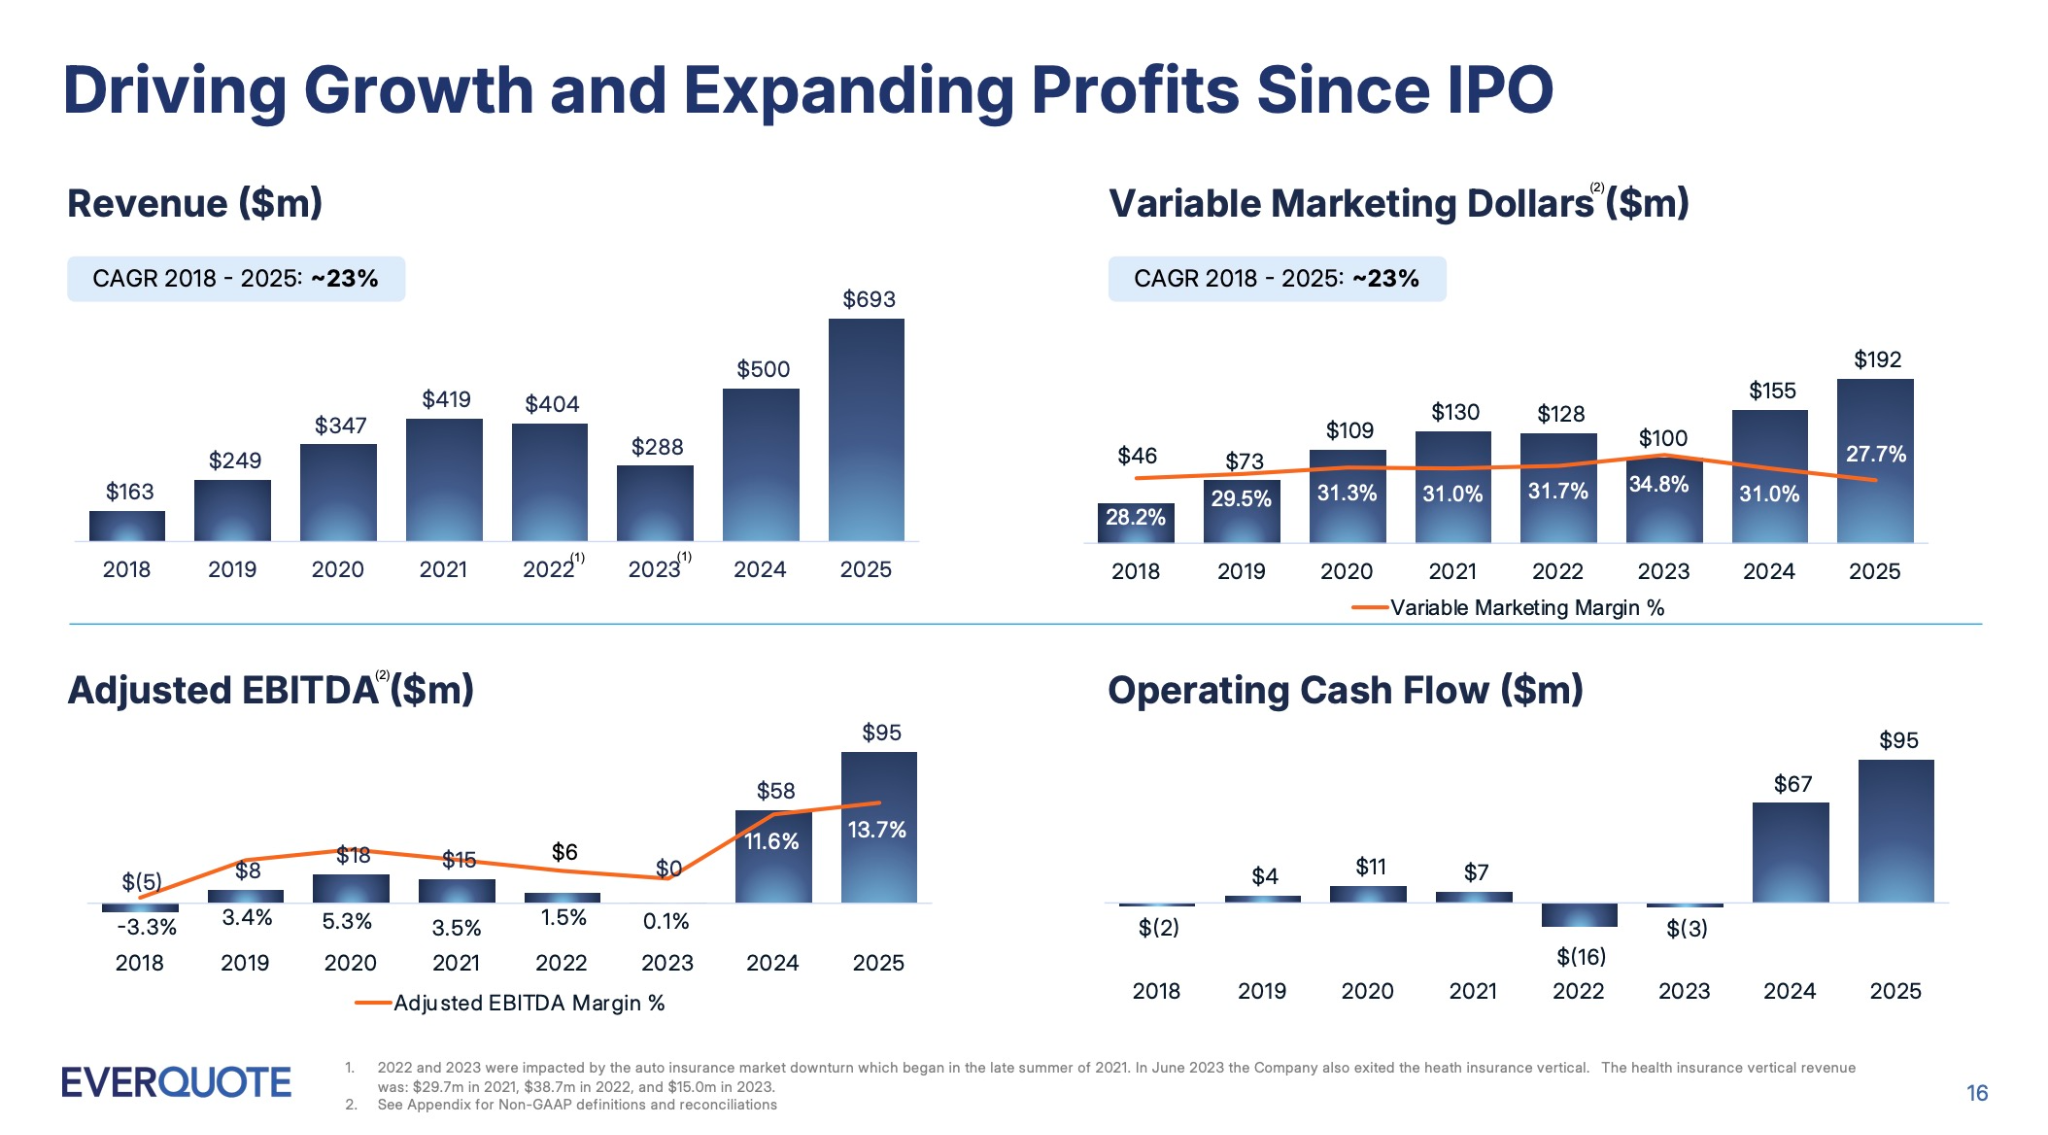
Key Takeaway: With $385MM in revenue already this year, EverQuote seems poised to top one billion dollars in annual revenue
2. They’re expanding beyond Auto
Auto Insurance is the undisputed king of volume and revenue in lead generation. It makes sense that they’d try to scale up the other insurance trades
Home and Renters insurance made $23MM of revenue in Q2, up from $18.5MM in Q1.
Key Takeway: While Auto remains the majority of revenue, EverQuote is having success growing Home and Renters insurance.
3. EverQuote gave some color on their AI usage
I doubt any companies on the index don’t mention AI in every announcement. That said, it’s refreshing that EverQuote offers some explanation about how they use AI in their business.
Per CEO Jayme Mendal:
“Our SmartCampaigns AI bidding solution continues to scale, supporting customers’ aggressive customer acquisition goals by helping them deploy marketing budgets more effectively and efficiently. 7 of our top 10 carriers now use SmartCampaigns”
And then continuing on to other applications:
“To name just a few, recent examples include AI Agents designed to emulate human shopper personas and identify friction points in our web experiences; as well as upgrades to our AI traffic bidding platform, which put us on a path to increasingly agentic traffic operations.”
Key Takeaway: 70% of their top carriers are using an AI bidding solution
4. They’re well capitalized
EverQuote ended Q2 with $192.3 million in cash (and equivalents) and no outstanding debt. They also set a new record for adjusted EBITDA at $30.1MM.
Also interesting to note that they listed $138.2MM of advertising expense in Q2. That represents 70.84% of the quarterly revenue, which is fairly flat relative to Q1. That suggests EverQuote has an estimated gross margin of 29% (or what some people call Media Margin).
Key Takeaway: EverQuote has a lot of cash with a steadily growing business.
5. Their Q3 forecast is up 17% YOY
From Joseph Sanborn, CFO
“We expect revenue to be between $198.0 and $208.0 million. Representing 17% year-over-year growth at the midpoint.
And we expect Adjusted EBITDA to be between $28.0 and 31.0 million. Representing 18% year-over-year growth at the midpoint.”
Key Takeaway: EverQuote expects business to increase in the near-term