

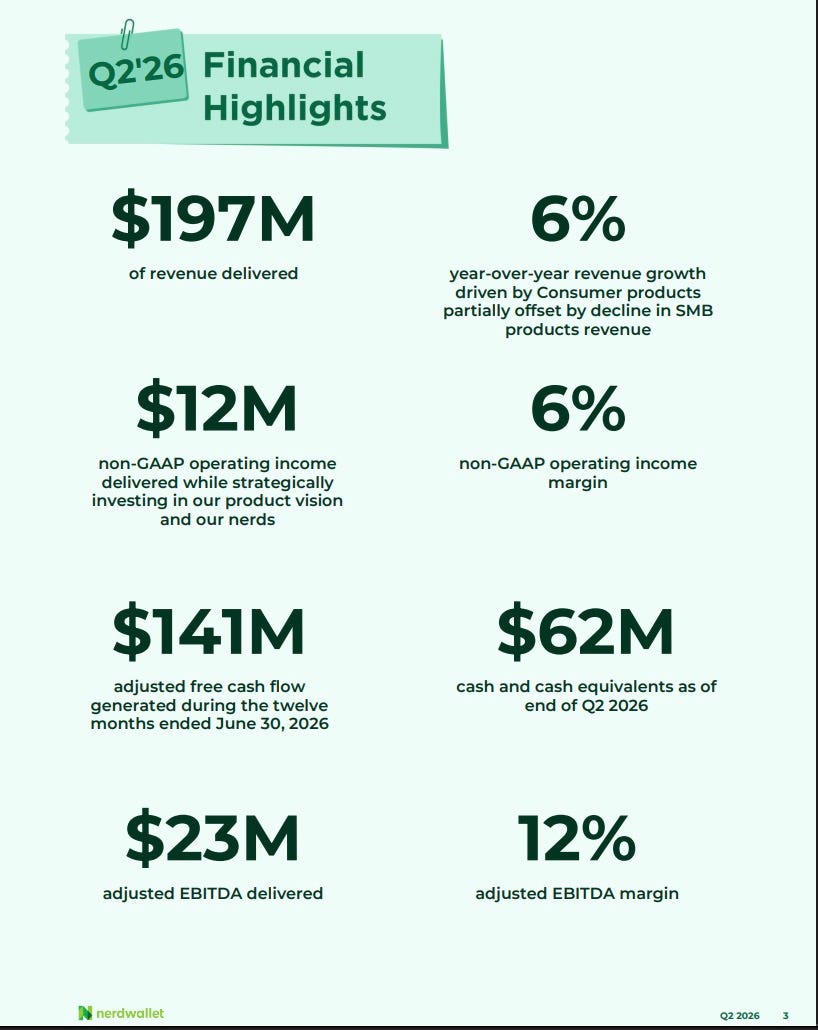
Stats (all QOQ)
Revenue down 11% (but up 6% YOY)1
Cash and equivalents up 10%
EBITDA down 49%
Liabilities down 20%
Shareholder equity down 3%
Five Observations
1. NerdWallet Acquired a Student Loan Marketplace
They acquired College Finance Company, LLC back in February for $17.2MM in cash. They mention that the acquisition is a marketplace that connects borrowers with lenders.
Key Takeaway: NerdWallet is investing into expanding their Student Loan offering.
2. SMB is down 11% YOY
NerdWallet’s SMB category appears to be primarily business loans.
“SMB revenue of $22.1 million was down 11% year-over-year, primarily due to continued pressures in organic search traffic, partially offset by an increase in business loan originations.”
Key Takeaway: Demand for Small Business loans is decreasing.
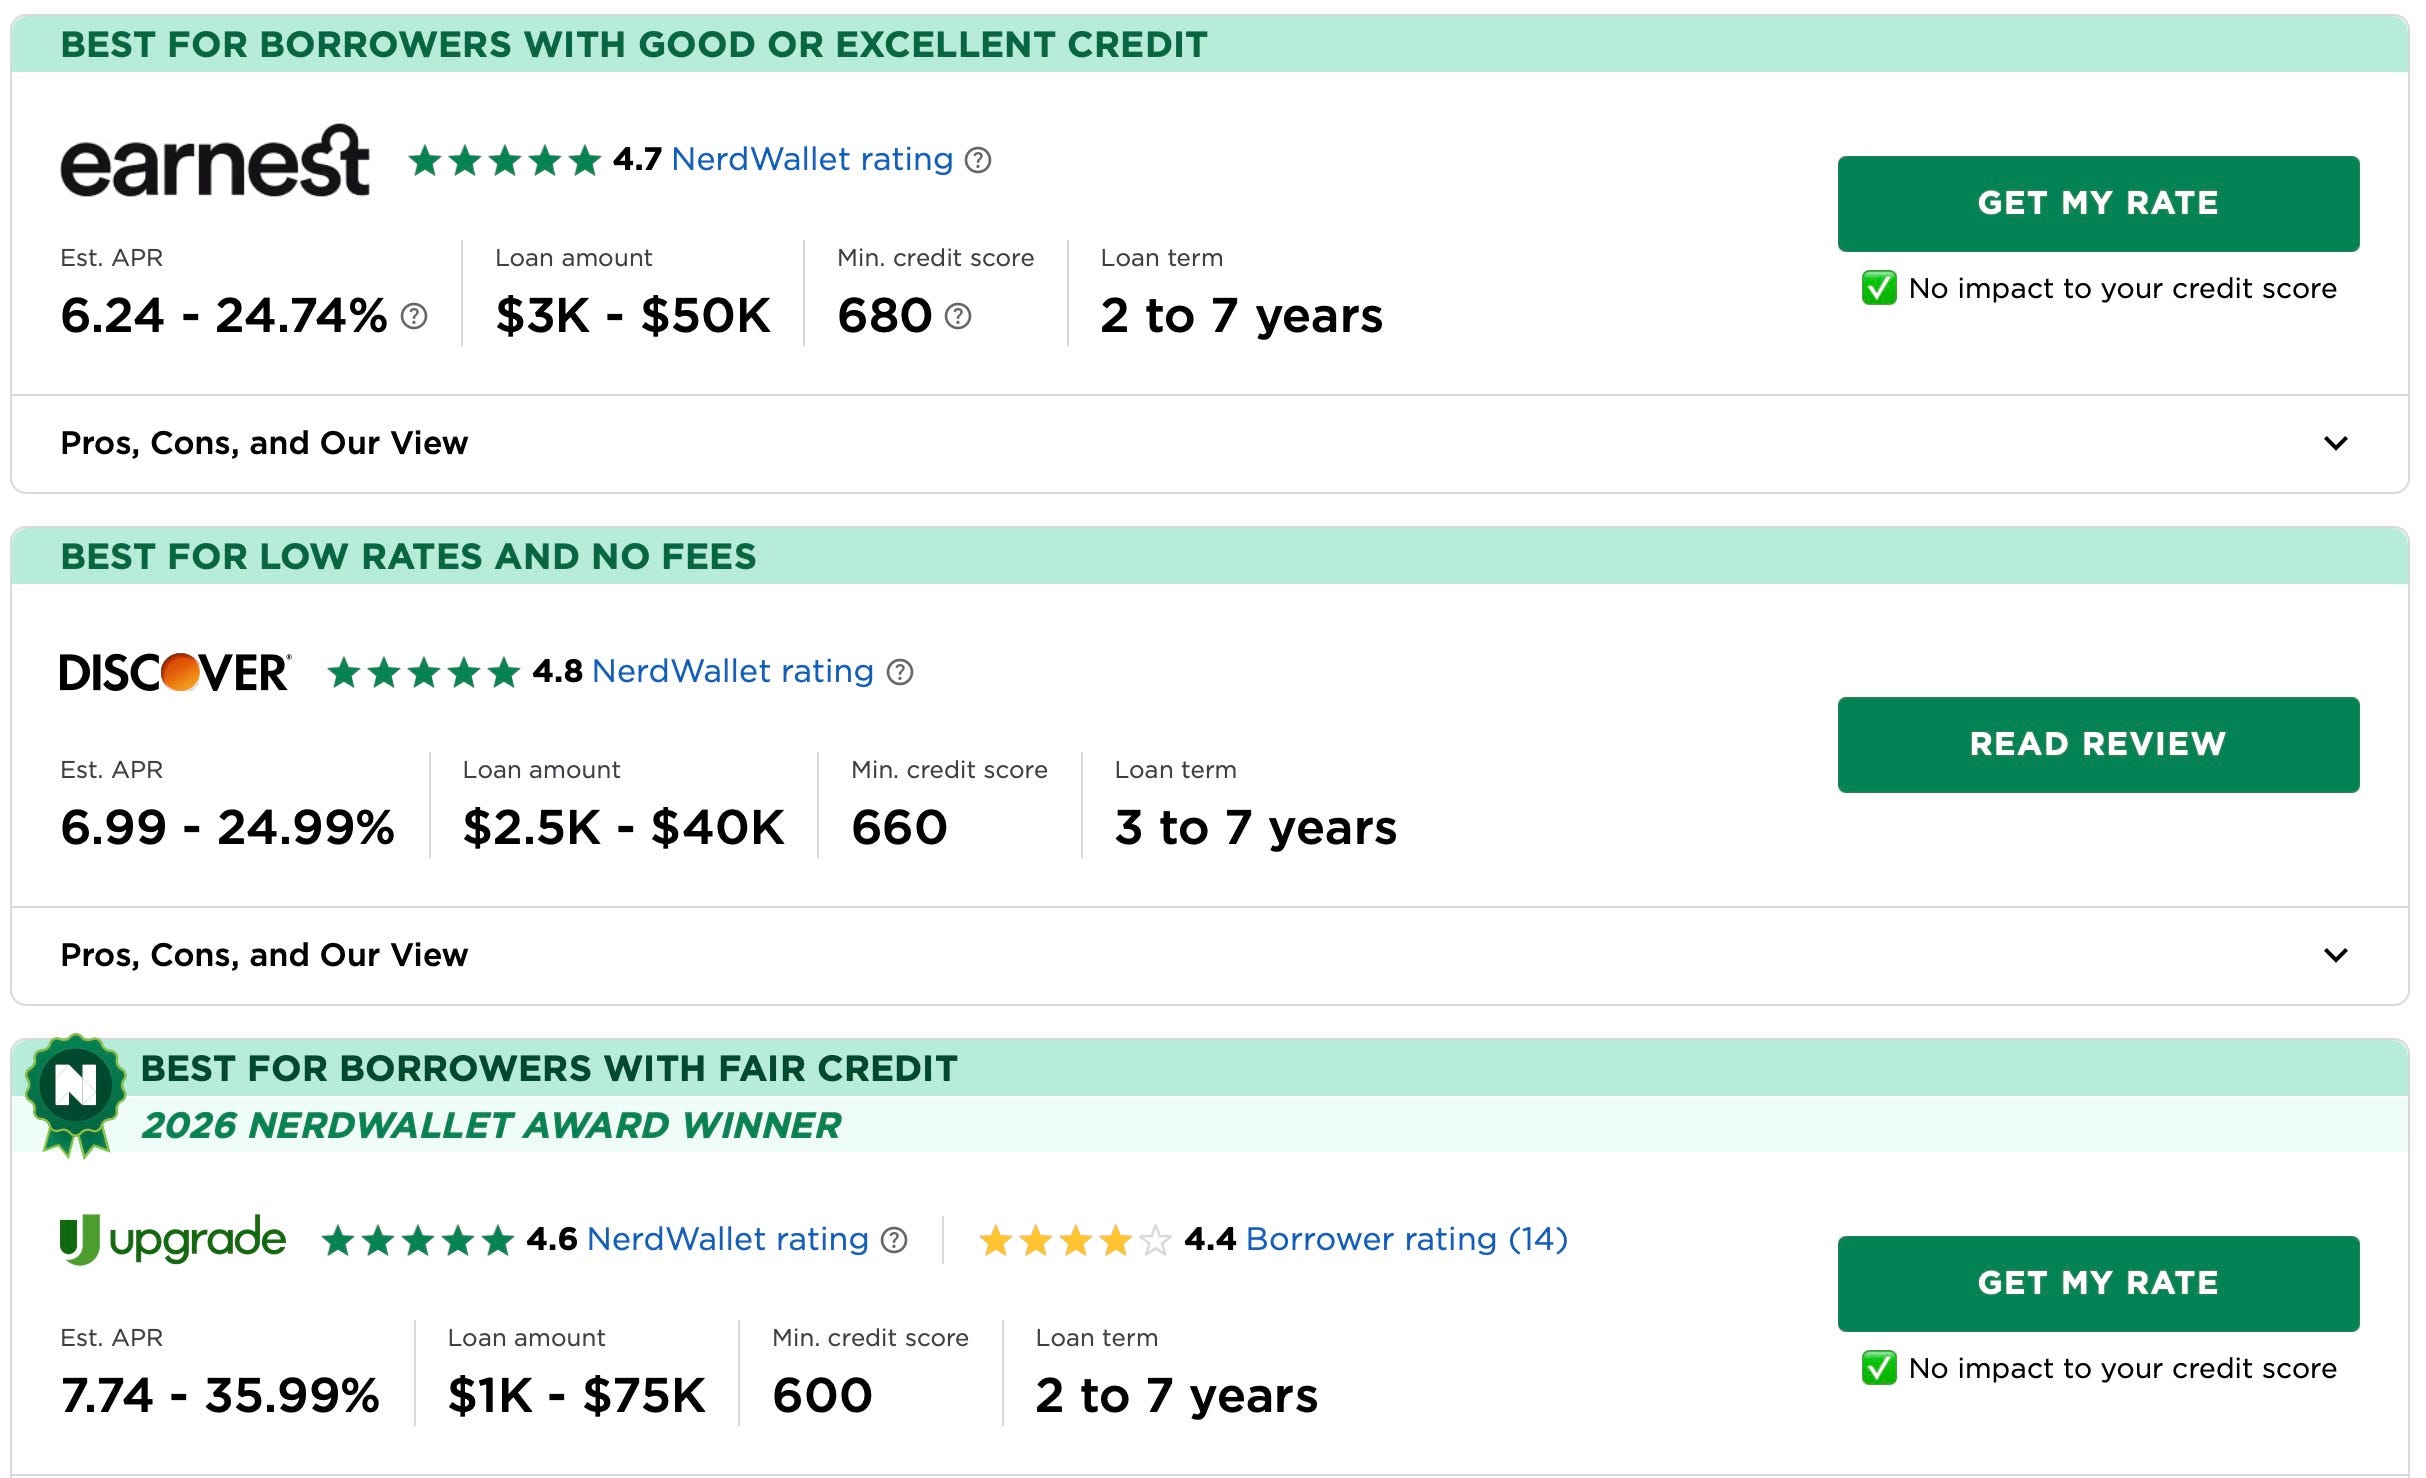
3. Personal Loans is expanding
From the earnings announcement:
“In personal loans, we expanded our marketplace to serve a broader range of borrowers by adding lenders and delivering more offers to near-prime consumers, which contributed to a $12 million year-over-year increase in personal loans revenue in the second quarter. As we build relationships with more lenders in this market, we are able to provide credit alternatives that can result in meaningfully better financial outcomes for near-prime consumers.”
The growth seems to be primarily driven by expanding into subprime as well as near-prime.
From the shareholder letter:
“We are making it easier for consumers to find the financial products that best meet their needs, and one of the areas where this is having the greatest impact is in the below-prime segment of the personal loans market.”
NerdWallet made their bones on Prime and Super-prime, so it’s not surprising to see them expand to grow their addressable market. To clarify credit ranges, the CFPB defines Subprime as 580-619 and Near-prime as 620-659.
Key Takeaway: NerdWallet is going downmarket to expand beyond Prime credit
4. Credit Card revenue is declining
From the announcement:
“Credit card revenue was down $8.6MM YOY primarily due to continued pressures in organic search traffic that have persisted for multiple quarters.”
I think it’s interesting that they specify that organic traffic has been dropping for many months. This indicates consumers aren’t looking for more credit cards.
If you compare that to these charts on consumer debt and delinquencies, it seems like a lot of Americans are struggling. It would make sense that card volume is down while Personal Loans (often used to consolidate cards) are up.
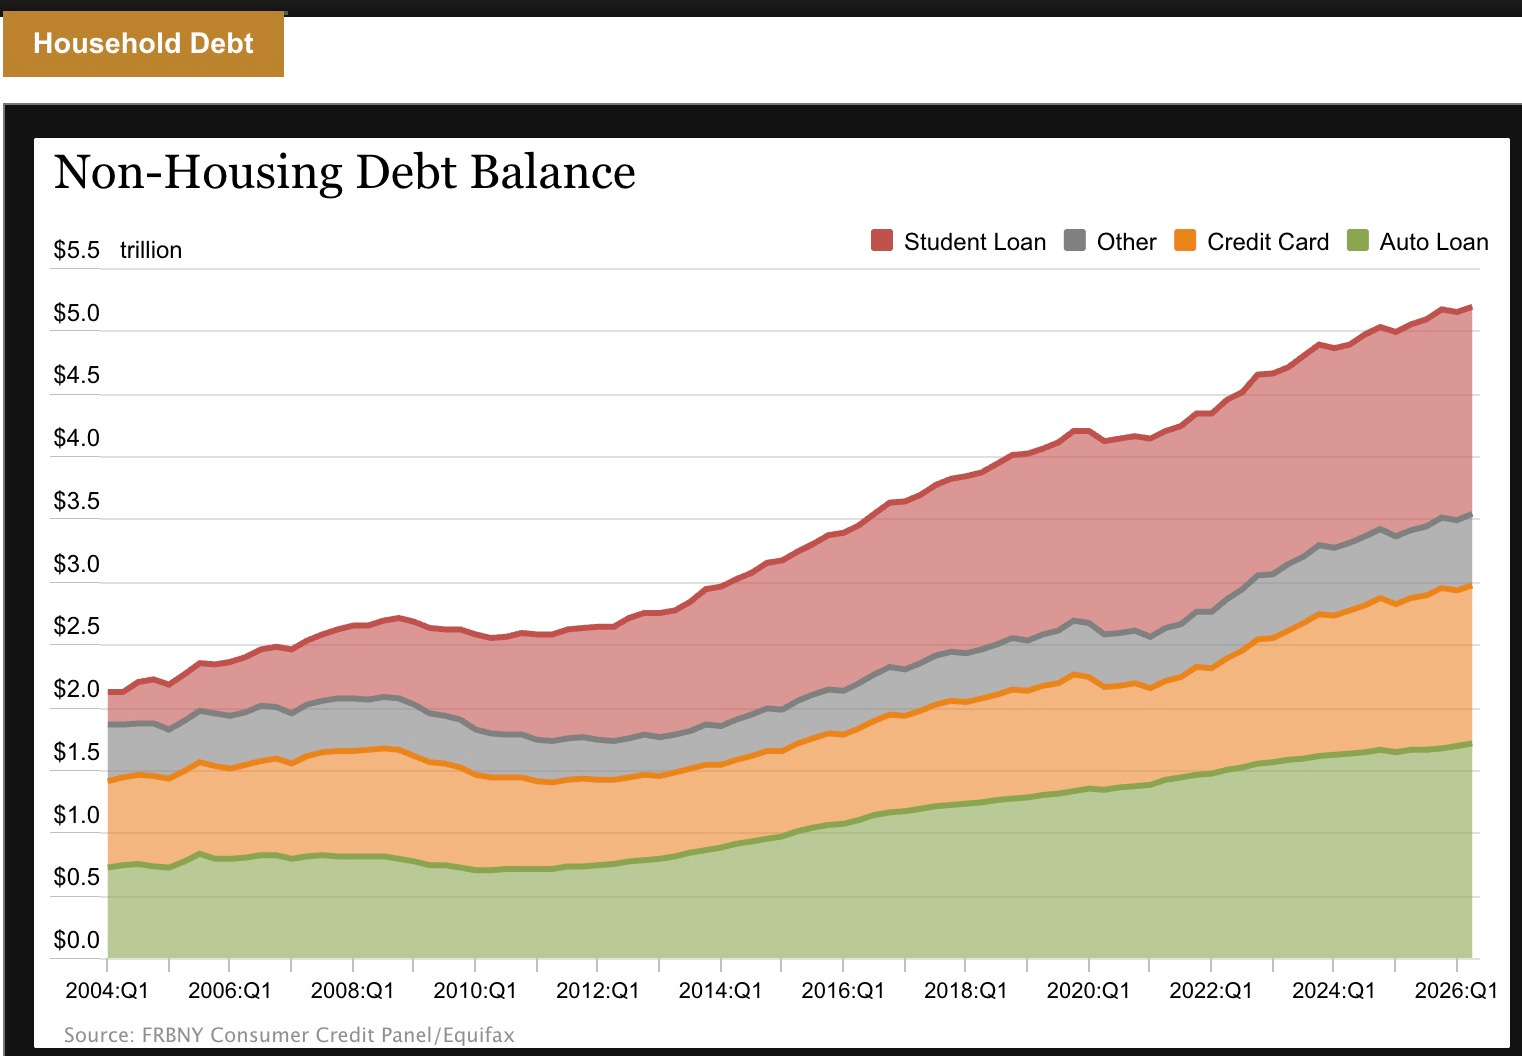
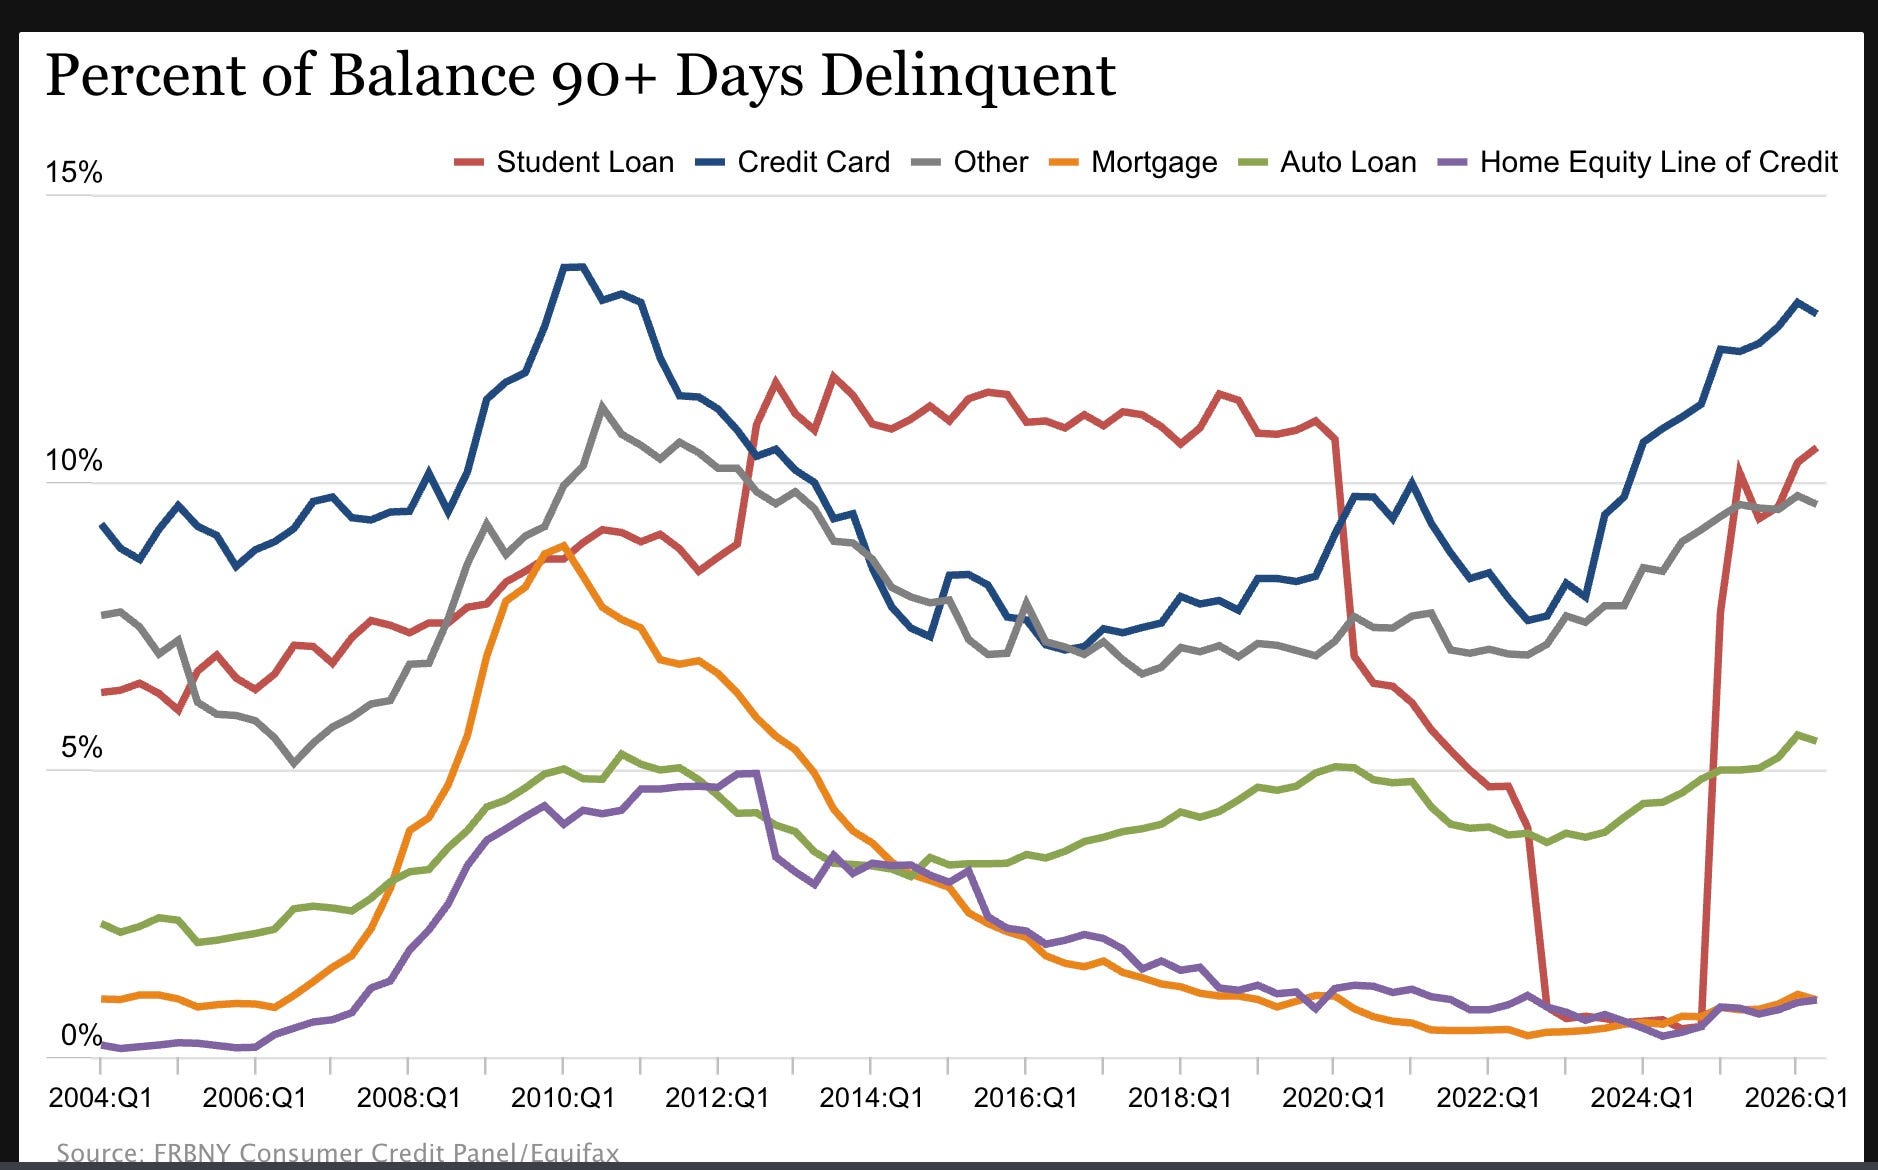
Key Takeaway: Consumer finance is shifting with higher debt and delinquency
5. In-house insurance policies nearly doubled
NerdWallet launched this initiative in March 2025 so it’s not a shock that it would have rapid growth in the early stages.
“Policies sold through our in-house insurance agency, NerdWallet Insurance Experts, nearly doubled quarter over quarter as our agents ramped their productivity. We continue to add licensed agents while deepening technology integrations with auto insurance carriers in order to build longer-term, recurring relationships with consumers.”
What’s interesting is that they give a hint about the motivations behind why they started selling insurance in-house.
From CFO Jun Lee on the earnings call
“Our largest auto insurance carrier relationship has stabilized, but not yet returned to levels seen earlier in the year. As we continue to explore ways to grow with that carrier, we remain focused on scaling with other leading auto insurance carriers and expanding our in-house insurance agency, an example of our growth and owned audiences.”
Key Takeaway: Their largest auto buyer is spending less, but NerdWallet is growing in-house policies
Final Notes
NerdWallet is aggressively repurchasing its shares. I don’t give stock-buying advice here, but it does seem a strong signal that NerdWallet is buying back shares at this rate. There are a number of reasons companies repurchase shares, but one of the most common is if they feel the stock is undervalued.
“The remaining share repurchase authorization under the Repurchase Program is $67.0 million as of June 30, 2026.”
Finally, NerdWallet raised guidance for Q3
“Revenue is expected in the range of 244-260 million, up 17% year-over-year at the midpoint”
NerdWallet mentions the seasonality issue with Q3 is expected, so the YOY number growing is more relevant than my preference for quarterly comparisons. “Our Q3 guidance reflects typical seasonality in our business as well as expected tailwinds from regulatory changes in student loans and the impact of our college finance acquisition in February”