

Key Stats (all QOQ)
Revenue up 8%
EPS up 254%
Cash on hand up 26%
Home Services Revenue up 24%
Insurance revenue flat
Gen/Admin expense down 19%
Selling/Marketing expense up 20%
Shareholder equity up 4%
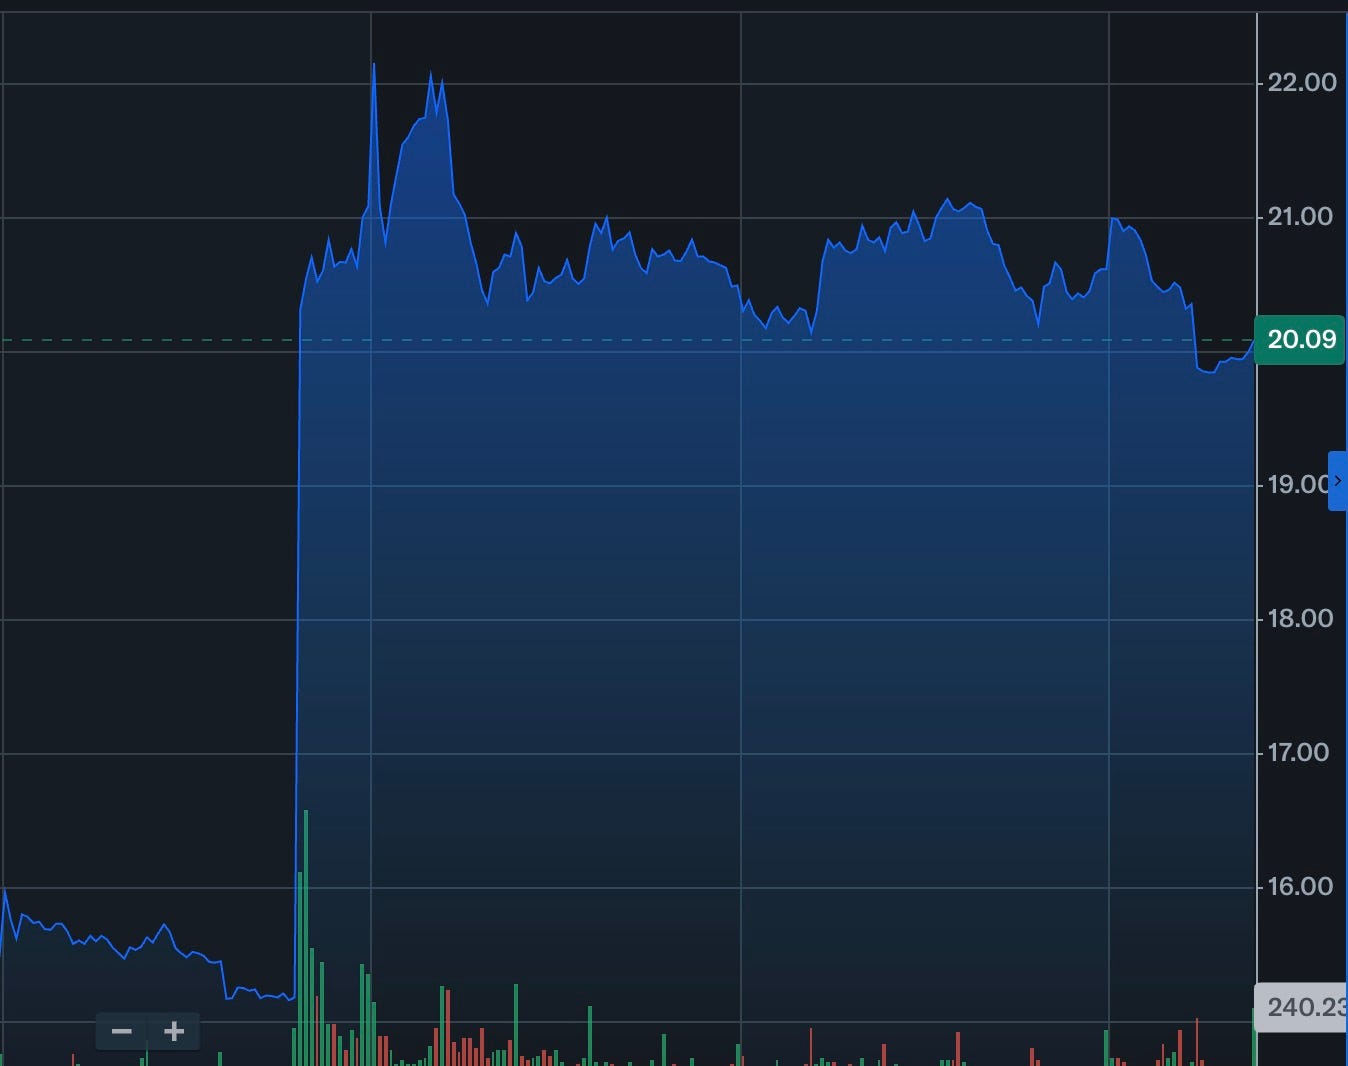
Five Observations
1. The HomeBuddy Acquisition price was ~$190MM**.
The actual/final “price” can fluctuate based on contingencies, but that’s basically what QuinStreet paid. The deal was structured as $115MM in cash and $75MM in stock. Personally, I was a bit surprised to see them go into debt to fund the purchase. Clearly they thought this was a strategic enough acquisition to finance it.
Key Takeaway: QuinStreet is investing heavily in Home Services, and seems to believe the HomeBuddy acquisition was highly strategic.
2. HomeBuddy generated $141MM of annual revenue
(In the 12 months before the acquisition). This implies a revenue multiple of 1.35X. EBITDA multiple was around 6.33x.
From the acquisition Press Release announcing the deal closing on 1/5/26:
“QuinStreet expects the acquisition of HomeBuddy to be accretive to its adjusted EBITDA and EPS, adding an expected $30 million or more to adjusted EBITDA in the first twelve months following closing of the transaction, with significantly more margin dollars expected to be added as the Company implements identified synergies from the combination.”
Key Takeaway: Large acquisitions are still possible for those who achieve scale.
3. Financial Services is their largest revenue category.
The category includes Insurance, Credit Cards, Personal Loans, and Banking. Revenue was flat QOQ,
Key Takeaway: Home Services is driving the revenue growth.
4. QuinStreet broke Quarterly and FY records
From the press release:
Record quarterly Revenue of $373.9 million, up 43% year-over-year
Record quarterly Net Income of $19.1 million, up 496% year-over-year
Record quarterly Adj. EBITDA of $41.4 million, up 87% year-over-year
Record Full Fiscal Year Revenue of $1.3 billion, up 18% year-over-year
Record Full Fiscal Year Net Income of $81.2 million, up 1,626% year-over-year
Record Full Fiscal Year Adj. EBITDA of $112.5 million, up 38% year-over-year
Not surprisingly, they’re predicting a strong FY27.
From the earnings call:
“Turning to our outlook, we expect revenue in fiscal Q1 to be between $370 and $380 million, implying 31% growth year-over-year at the midpoint of the range. We expect adjusted EBITDA to be between $38 and $40 million, implying 90% growth, a 10.4% margin and a 320 basis-point margin expansion year-over-year at the midpoint of the range.”
Key Takeaway: With a strong finish to their fiscal year, QuinStreet seems to be on the upswing leading into FY27 and calendar Q3.
5. Investment in Home Services has paid off big
I have to give some credit to the QuinStreet leadership team here. Back in 2019, they were in far more categories, such as Education, B2B, Mortgage, and others. Before they acquired Modernize in 2020, QuinStreet sold off several of those lines of business.
Back in 2019, Home Services wasn’t even split out in its own category for SEC filings; it was lumped together with B2B.
Total combined net revenue in FY19 for Home Services/B2B was just under $55MM. Now, Home Services is generating over $400MM of annual revenue. That likely represents more than an 8x increase over the last 7 years. Seen through this lens, the HomeBuddy acquisition is simply a continuation of the strategy from 2019-20.
Key Takeaway: QuinStreet shrewdly pivoted out of lower-growth categories to focus fully on Home Services and Financial Services.

Disclosures
*QuinStreet operates on a Fiscal Year from July through June. So while Calendar Q2 just ended, QNST just wrapped up Q4 of their Fiscal Year.
**I worked at QuinStreet from 2020-2025. I previously owned QNST stock granted as RSU’s/PSU’s, but no longer own any shares.
I also introduced one of the HomeBuddy founders to the QuinStreet Corporate Development team, but was not otherwise involved in the deal. As always, I use only data from SEC filings, and any conclusions are my interpretation of that data.