

Stats (all QOQ)
Net Income up 78%
Revenue up 4%
Cash and equivalents down 15%
Adjusted EBITDA up 15%
Shareholder Equity up 2%
Liabilities down 9%
Much like LendingTree is an Insurance lead generation company with a Mortgage background, Yelp is a Home Services advertising platform with a Restaurant background. They were not originally included in The Lead Index but I explain the reasons for their recent inclusion below the main content here.
5 Observations
1. Hatch is Growing Fast
In January, Yelp announced they were buying Hatch for $300MM ($270MM cash and $30M in retention bonus pool). For those unfamiliar, Hatch is leveraging AI call agents and touts their ability to help companies with things like call handling, speed to lead, lead nurturing, etc. Their primary focus is customers in Home Improvement.
From the announcement:
“As of November 2025, Hatch had achieved approximately $25 million in annual recurring revenue.”
I was a little surprised to see the revenue multiple at 12X. Median SaaS multiples these days are around 4.5x of revenue. However, AI multiples are more in the 25-30x range. I could see Yelp blending those to support the deal price.
From the Shareholder Letter:
“Hatch annual run rate revenue grew 59% year over year to $35 million in June”
While run rate and ARR are not quite the same thing, the numbers do indicate fairly impressive growth of Hatch. It makes sense that plugging a platform into a company with
Key Takeaway: Yelp paid a premium to expand Home Services and AI capabilities
2. Yelp is all-in on AI
Yelp framed Hatch as an “AI Lead Management Platform” in the original announcement.
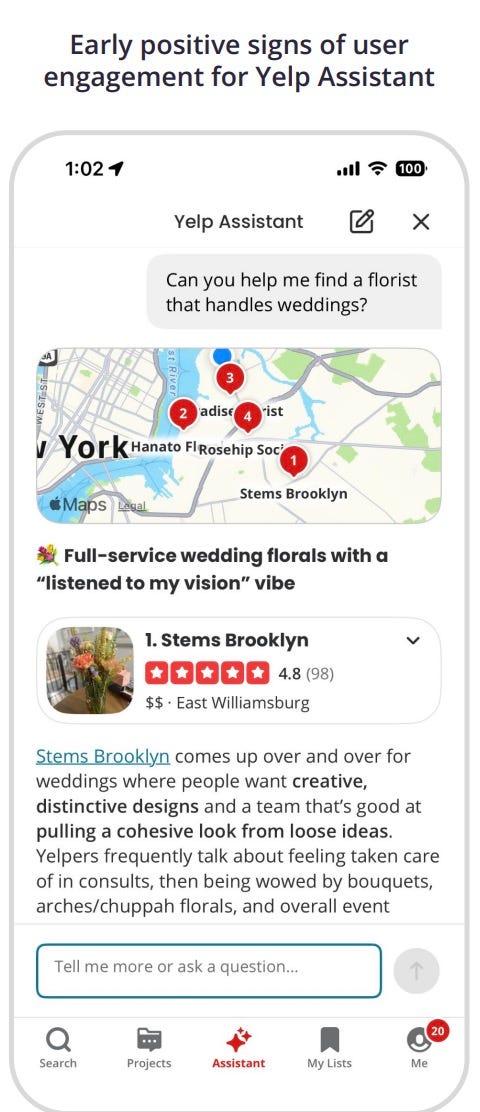
Yelp Assistant is essentially an AI bot in the app that answers user questions and allows consumers to reserve a table or get quotes for a project, etc. I was intrigued to see that it’s driving a solid chunk of lead volume
From the shareholder letter:
“Yelp Assistant generated approximately 10% of Request-a-Quote projects, contributing to overall project growth of approximately 10% year over year.”
They seem to be having success licensing all of their data to AI companies as well.
From the Shareholder Letter:
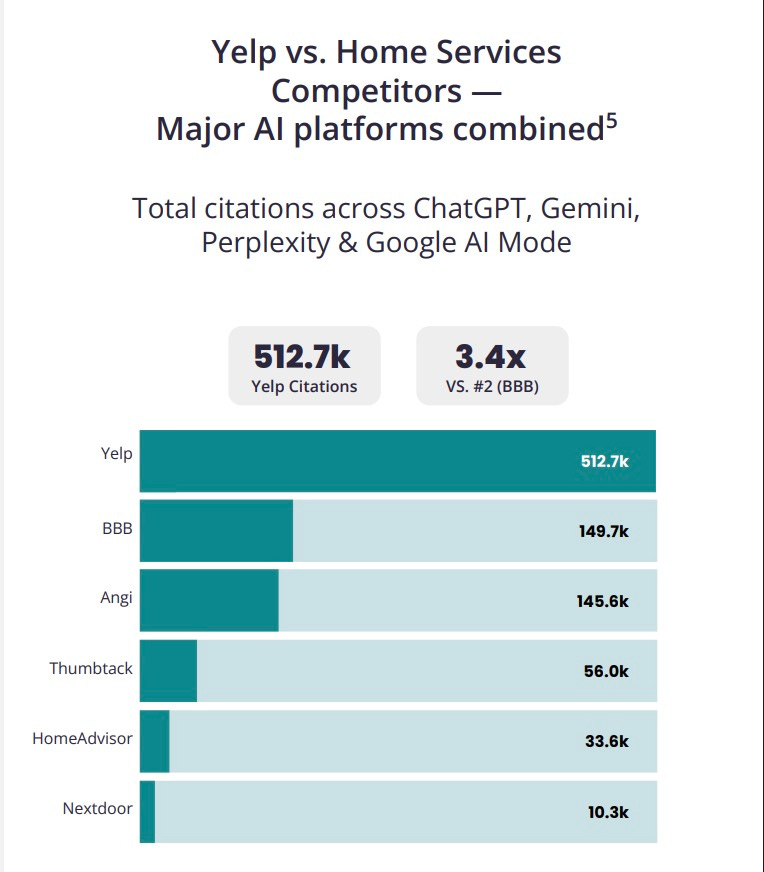
“Demand for our data licensing products was robust in the second quarter, including from our partnership with OpenAI, contributing to strong growth in other revenue. Yelp ratings and reviews recently began powering ChatGPT’s local experience in relevant categories. Building on our success with Apple Maps and Yahoo, we also expect Request-a-Quote integration with ChatGPT to launch in the coming weeks.”
Also find it interesting that they specify Home Services on the AI citations. Perhaps that data is proving more useful than their restaurant data, but that’s purely conjecture on my part.
Key Takeaway: Yelp’s AI strategy seems to be paying off
3. Services is their largest revenue segment
It’s a little opaque as they have three buckets of revenue. Advertising is broken up between
Services and Restaurants, Retail & Other. Services is 2.37X the revenue of Restaurant, Retail, and Other combined.
Here’s the breakdown for Q2:

From the 10Q:
“Our Services categories consist of home, local, auto, professional, pets, events, real estate and financial services”
Outside of advertising, they have Other, which they define as
Other Revenue is a variety of other tools, including Hatch. Also from the 10Q:
“We generate other revenue through non-advertising contracts, such as our subscription services, which include our Yelp Guest Manager, Yelp Receptionist, Yelp Host and Hatch offerings, as well as our Yelp Places, Yelp AI, and Yelp Insights API programs, which provide Yelp content and data for a fee. In addition, other revenue includes revenue from various transactions with consumers.”
Restaurant and other was actually down YOY:
“Advertising revenue from Restaurants, Retail & Other (“RR&O”) businesses decreased by 10% year over year, driven by decreases in ad clicks and average CPC. These results, as well as decreases in both RR&O paying advertising locations and average revenue per location, reflect the challenging operating environment for local businesses in these categories and, to a lesser extent, competitive pressures from food ordering and delivery providers. However, ad clicks, average CPC and paying advertising locations in RR&O improved compared to the first quarter of 2026.”
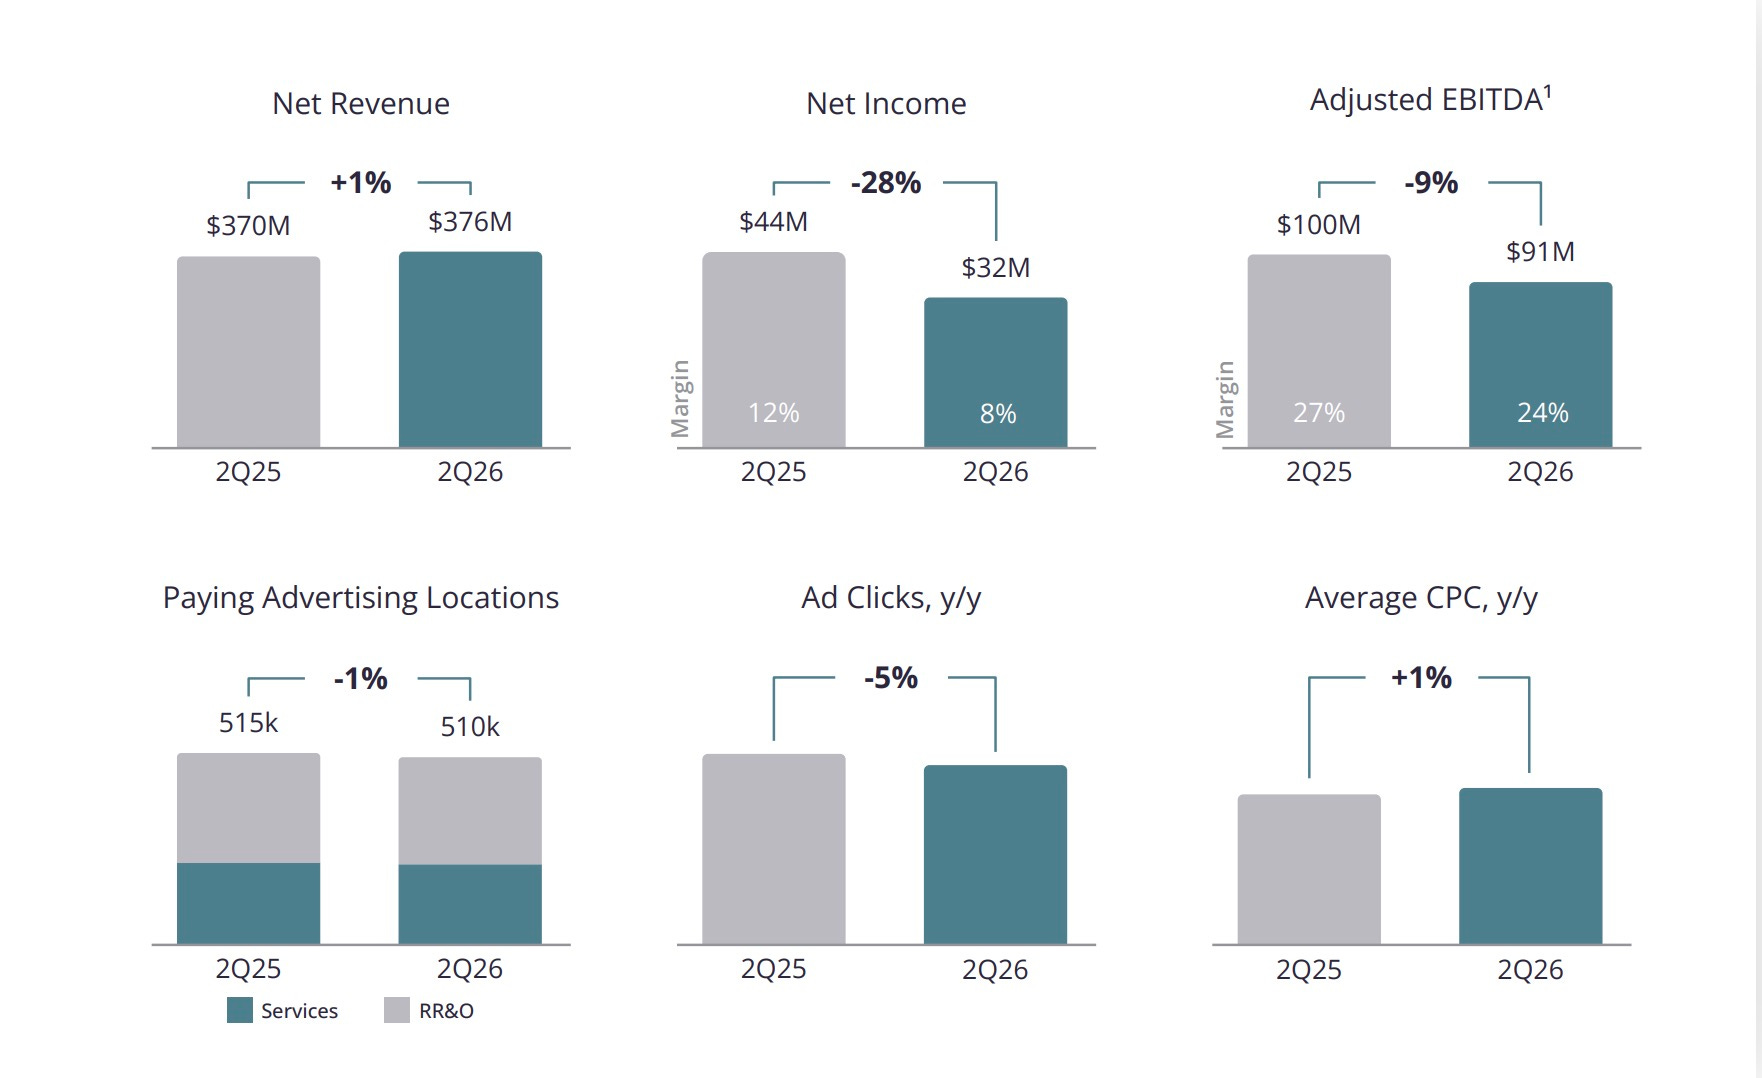
Across the org, clicks were down 5% YOY, but CPC was up 1%. Yelp explains in the Shareholder Letter that they have higher CPCs in Services than Restaurant & Other:
“Average CPC increased by 1% as Services ad clicks, which generally have higher CPCs than RR&O categories, comprised a greater portion of total ad clicks compared to the prior-year period.”
Anecdotally, I went to a Yelp Partner Summit in March. It included a mix of advertisers and agencies. While not scientific, it felt to me like 75%+ of the attendees were focused on Home Services.
Key Takeaway: Yelp is Investing Heavily in Home Services
4. Yelp Has Massive Scale
As I mentioned in the intro, I think a lot of people still see Yelp as a restaurant app.
In Q2, Yelp had 510,000 advertising locations. Locations are the important distinction because many advertisers are multi-location, so that connects more to all of the Yelp pages that advertise.
From the Shareholder Letter:
“In 2026, we now expect net revenue to be in the range of $1.460 billion to $1.470 billion and adjusted EBITDA to be in the range of $315 million to $325 million”
Key Takeaway: Yelp is one of the Biggest Advertising Players
5. Yelp is Doing a Massive Stock Buyback
They’ve already purchased $175.1MM worth of stock in the first 6 months of 2026.
From the 10Q
“On February 10, 2026, the Company’s board of directors authorized a $500.0 million increase to its stock repurchase program, bringing the total amount of repurchases authorized under the stock repurchase program since its inception in 2017 to $2.45 billion of its outstanding common stock, $363.7 million of which remained available as of June 30, 2026.”
As I mentioned in the NerdWallet analysis, there are many reasons a company might repurchase shares. Buybacks can offset dilution, create tax efficiency, prevent hostile takeovers, and signal confidence. They also return capital to shareholders and lift EPS. At a high level, though, it often means the company believes its shares are undervalued.
Key Takeaway: Yelp is Signaling Confidence in Their Business
Why cover Yelp in The Lead Index
I originally had Yelp just outside the list and on the bubble. The reason I changed my tune is that I think Yelp is really ramping up lead gen in a way that many people don’t realize. Despite charging for advertising on a CPC, I believe they’re becoming something closer to Modernize than Google.
They generate and track leads through their RequestAQuote. They have far more dollars in Home Services than you might expect. With the Hatch acquisition, they’re actively in the lead management/follow up game - helping advertisers convert their leads. That feels pretty lead gen to me.
Summary
I have some ideas for topics I’ll tackle the next couple of weeks before more earnings reports come out. However, I'd love to know what the readers want to see here. Please put it in the comments or email me at info@theleadindex.com.
Additional Yelp Disclosures
UpScale Growth and my previous company were both previously Yelp Agencies. UpScale isn’t currently an active Yelp Agency, but I expect we will be again in the near future.
I have previously advertised one of my businesses on Yelp.
As always, I draw my conclusions from the SEC filings, but sometimes I’ll offer a personal anecdote, and I will always flag it as such when it comes up.
